Pag-IBIG housing loan interest rates 2026
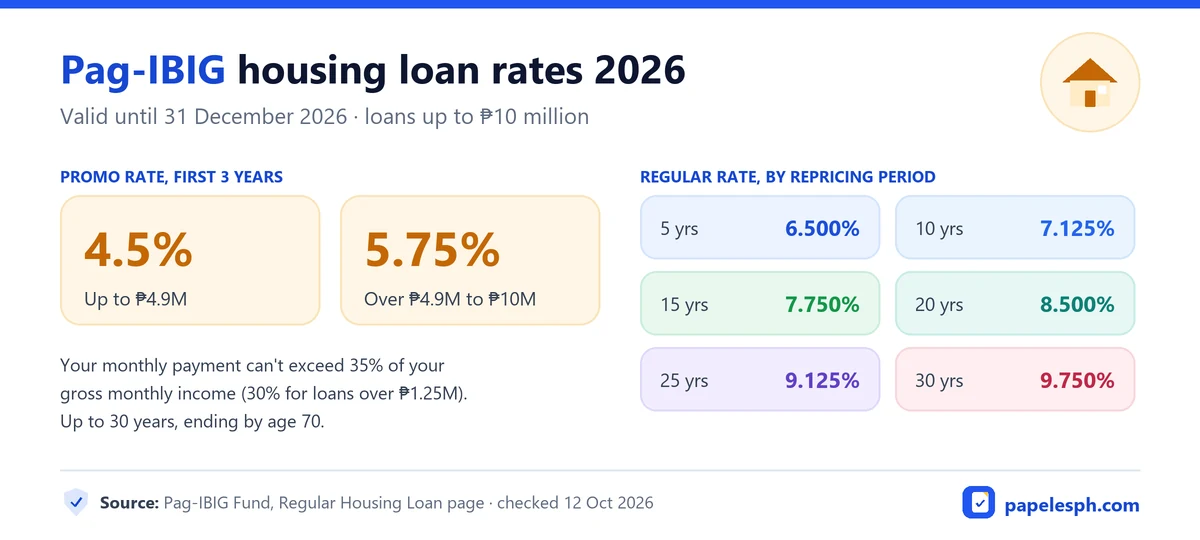
Pag-IBIG Fund's rates until 31 December 2026:
Promo rates (first 3 years of the loan term)
| Loan amount | Promo rate |
|---|---|
| Up to ₱4.9 million | 4.5% |
| Over ₱4.9 million up to ₱10 million | 5.75% |
Regular rates (by repricing period)
| Repricing period | Interest rate |
|---|---|
| 5 years | 6.500% |
| 10 years | 7.125% |
| 15 years | 7.750% |
| 20 years | 8.500% |
| 25 years | 9.125% |
| 30 years | 9.750% |
What's a repricing period? It's how long your interest rate stays fixed. When it ends, Pag-IBIG reprices your loan to its rate at that time. A longer fixed period costs a higher rate. Pag-IBIG doesn't publish which rate applies after the 3-year promo. Circular No. 396 only says rates are repriced periodically under Pag-IBIG's risk-based pricing, based on the repricing period you choose, so ask for your post-promo rate when you apply.
Sample monthly amortization
Principal and interest only, before insurance, using the calculator's formula:
| Loan | 4.5% promo, 30 years | 6.5%, 30 years | 6.5%, 20 years |
|---|---|---|---|
| ₱1,000,000 | ₱5,066.85 | ₱6,320.68 | ₱7,455.73 |
| ₱2,000,000 | ₱10,133.71 | ₱12,641.36 | ₱14,911.46 |
| ₱3,000,000 | ₱15,200.56 | ₱18,962.04 | ₱22,367.19 |
How the calculator works
- Monthly payment: the standard amortization formula, with your annual rate divided by 12 and your term in months.
- Promo rate: picks 4.5% for loans up to ₱4.9 million and 5.75% above that. It applies to the first 3 years only, so the result is your payment for those years.
- Age check: your loan must be fully paid by age 70, and you must be 65 or younger when you apply, so the calculator warns you if your term is too long.
Your real monthly payment is higher. Every Pag-IBIG Housing Loan carries Mortgage Redemption Insurance (or Sales Redemption Insurance) and Fire and Allied Perils Insurance, added to your amortization. For an official estimate with insurance, use Pag-IBIG's own Housing Loan Affordability Calculator.
Who can get a Pag-IBIG housing loan
From Pag-IBIG Fund's Housing Loan FAQs, you need:
- At least 24 monthly membership savings (you may pay the required months in a lump sum)
- To be 65 or younger when you apply, and 70 or younger when the loan matures
- Legal capacity to encumber (mortgage) real property
- To pass Pag-IBIG's background, credit and employment or business checks
- No Pag-IBIG short-term loan in arrears (like the Multi-Purpose Loan)
- No Pag-IBIG housing loan that was foreclosed, cancelled, bought back due to default, or settled by dacion en pago
- If you already have a Pag-IBIG housing loan (as borrower or co-borrower), it must be updated
You can add up to two co-borrowers. Not a member yet? Get your Pag-IBIG MID number and start your monthly contributions.
How much you can borrow
Up to ₱10 million, but Pag-IBIG lends the lowest of:
- your actual need,
- your desired loan amount,
- your loanable amount based on your capacity to pay, and
- the loan-to-appraised value ratio of the property.
Capacity to pay: the 35% rule
Under Pag-IBIG Circular No. 396 (section 4.1.2), your monthly repayment can't exceed:
| Loan amount | Monthly payment limit |
|---|---|
| Up to ₱1,250,000 | 35% of your gross monthly income |
| Over ₱1,250,000 | 30% of your gross monthly income |
Example: a ₱2 million loan at the 4.5% promo rate over 30 years is about ₱10,133.71 a month, so you'd need a gross monthly income of at least ₱33,779 (₱10,133.71 ÷ 30%). Enter your income in the calculator above to check. Borrowing with co-borrowers? Each co-borrower's own income is counted.
Loan-to-appraised value (LTV)
The loan can't be more than this share of the property's appraised value:
| Loan amount | Maximum LTV |
|---|---|
| Up to ₱1,000,000 | 95% |
| Over ₱1,000,000 up to the economic housing loan ceiling | 90% |
| Over the economic housing loan ceiling up to ₱6,000,000 | 85% |
| Over ₱6,000,000 up to ₱10,000,000 | 90% (Circular No. 491, 2026) |
So you'll usually need a down payment for the rest. For developer-assisted loans for socialized housing units, the LTV can be 100%. For retail loans, Pag-IBIG may adjust the LTV based on its Borrower's Evaluation System.
What you can use it for
- A fully developed residential lot (or adjoining lots) of up to 1,000 square meters
- A house and lot, townhouse or condominium unit, brand-new or pre-owned, including a property mortgaged with Pag-IBIG or adjoining units
- Building or completing a house on a lot you or a relative own
- Home improvement
- Refinancing an existing housing loan, if you've paid on time (nothing more than 30 days late) for the last 6 months
Term, payments and the reserve payment
- Term: up to 30 years, but no longer than 70 minus your age today.
- Paying: through your employer (salary deduction), post-dated checks, auto-debit with a Pag-IBIG partner bank, Virtual Pag-IBIG, or accredited payment partners. Payments start the month after your loan is released.
- Late payments: any unpaid amount after the due date is charged a penalty of 1/20 of 1% for every day of delay (Circular No. 396). Your payments go first to penalties, then insurance, then interest, then principal.
- Housing Loan Reserve Payment: when your loan is released, one month's amortization is set aside from the proceeds. It keeps your insurance active and protects you from late penalties if a payment is delayed. You still pay your first amortization on time. Any unused reserve goes to your last amortization.
How to apply
Submit the housing loan application form and requirements at any Pag-IBIG branch, or through the accredited developer you're buying from. You can also start online: on Virtual Pag-IBIG, go to Apply for or Manage Loans and choose Apply for a Housing Loan.
Official sources
- Pag-IBIG Fund Regular Housing Loan page (rates, qualifications and FAQs): pagibigfund.gov.ph
- Pag-IBIG Circular No. 396 (9 January 2018, End-User Home Financing guidelines) and Circular No. 491 (26 May 2026, maximum loan of ₱10 million), linked from that page
- Pag-IBIG's official Housing Loan Affordability Calculator: pagibigfundservices.com/ac
Frequently asked questions
What is the Pag-IBIG housing loan interest rate for 2026?
Until 31 December 2026, Pag-IBIG offers a promo rate for the first 3 years: 4.5% for loans up to ₱4.9 million and 5.75% for loans over ₱4.9 million up to ₱10 million. Regular rates range from 6.5% (5-year repricing) to 9.75% (30-year repricing).
How much is the monthly amortization for a ₱1 million Pag-IBIG housing loan?
About ₱6,320.68 a month at 6.5% over 30 years, or about ₱5,066.85 at the 4.5% promo rate, in principal and interest. Insurance is added on top, so your actual payment is higher.
How much can I borrow from Pag-IBIG for a house?
Up to ₱10 million, but Pag-IBIG lends the lowest of your actual need, your desired amount, what you can afford based on your income, and the loan-to-appraised value of the property.
How much income do I need for a Pag-IBIG housing loan?
Your monthly payment can't exceed 35% of your gross monthly income for loans up to ₱1.25 million, or 30% for bigger loans, under Pag-IBIG Circular No. 396. For a ₱2 million loan at 4.5% over 30 years (about ₱10,134 a month), that's at least about ₱33,779 a month.
How many contributions do I need for a Pag-IBIG housing loan?
At least 24 monthly membership savings. Pag-IBIG allows you to pay the required months in a lump sum.
What is the age limit for a Pag-IBIG housing loan?
You must be 65 or younger when you apply, and the loan must mature by age 70. Your term can't be longer than 70 minus your age, up to 30 years.
Is this calculator official?
No. It's an independent estimate using Pag-IBIG's published rates. It shows principal and interest only. For Pag-IBIG's own figures, use its Housing Loan Affordability Calculator or ask a Pag-IBIG branch.
What is the Housing Loan Reserve Payment?
One month's amortization set aside from your loan proceeds at release. It keeps your insurance active and protects you from late penalties if a payment is delayed. Unused reserve is applied to your final amortization.
Keep reading
Pag-IBIG contribution
₱200 + ₱200 a month, OFW and self-employed rates, dividends and top-ups.
Read guidePag-IBIG Multi-Purpose Loan
Requirements, how much you can borrow, the rate and online steps.
Read guidePag-IBIG MID number
Register online, verify your MID, retrieve a lost number and update records.
Read guideSources
- Pag-IBIG Fund: Regular Housing Loan (rates until 31 December 2026, qualifications, FAQs)
- Pag-IBIG Fund Circular No. 396, Modified Guidelines on the End-User Home Financing Program (PDF)
- Pag-IBIG Fund Circular No. 491, maximum loanable amount of up to ₱10 million (PDF)
- Pag-IBIG Fund: Housing Loan Affordability Calculator (official)
- Virtual Pag-IBIG: apply for a housing loan
Last checked 12 October 2026. See how we research and the updates log.