Pag-IBIG Calamity Loan at a glance
| Pag-IBIG Calamity Loan | |
|---|---|
| Who | Members who live or work in an area under a declared state of calamity |
| When | Within 90 days of the declaration |
| How much | Up to 90% of your total Regular Savings, minus any outstanding MPL, Calamity Loan or HELPs |
| Interest | 5.95% a year |
| Terms | 12, 24 or 36 months (24 if you don't choose), plus a 3-month grace period |
| Processing | 2–3 working days (Pag-IBIG says "as fast as 3 days") |
| Paid to | Your cash card: a Pag-IBIG Loyalty Card Plus or a partner-bank cash card |
Is the Pag-IBIG Calamity Loan available now?
It opens area by area. There's no single nationwide application period. Under Circular No. 470, the loan is for members in areas declared under a state of calamity by the Office of the President or the Sangguniang Bayan (Pag-IBIG's page says "the LGU or the national government"). You then have 90 days from the declaration to apply.
So the question is whether your city or municipality is under a current declaration. Check with your LGU, or ask Pag-IBIG at (02) 8724-4244 or contactus@pagibigfund.gov.ph. If your area isn't covered, the Pag-IBIG Multi-Purpose Loan is open all year.
What counts as a calamity: Circular No. 470 covers man-made hazards and these natural hazards: typhoons, storm surges, tornadoes, landslides, earthquakes, tsunamis, volcanic eruptions, and El Niño and La Niña. For other causes, Pag-IBIG decides after an internal assessment approved by its Board.
Who qualifies
- Live in the declared area, or work in it. A workplace in a declared area is subject to Pag-IBIG management's approval.
- Apply within 90 days of the declaration.
- At least 12 monthly savings under Pag-IBIG Regular Savings. Fewer months is allowed if your total savings already equal 12 months' worth at your rate. If you withdrew your savings at maturity or through optional withdrawal, you need 12 new monthly savings after that.
- Active member: at least one monthly contribution in the last 6 months (12 months for OFWs).
- Any existing MPL, Calamity Loan or HELPs must not be in default.
- Proof of income.
How much can you borrow?
Up to 90% of your total Regular Savings: your contributions, your employer's contributions and the dividends. If you still owe on an MPL, Calamity Loan or HELPs, you get 90% of your savings minus that balance.
| Your total Regular Savings | Outstanding MPL, Calamity Loan or HELPs | Most you can get |
|---|---|---|
| ₱20,000 | None | ₱18,000 |
| ₱50,000 | None | ₱45,000 |
| ₱100,000 | None | ₱90,000 |
| ₱100,000 | ₱30,000 MPL | ₱60,000 |
Pag-IBIG approves the lowest of three amounts: what you ask for, your 90% entitlement, and what your pay can cover. The monthly payment can't push an employee's net take-home pay below the minimum set by the General Appropriations Act or company policy. You can choose Maximum Loan Amount on the form.
These are examples of Pag-IBIG's 90% rule, not quotes. Older posts online still say 80%. That was the old rule; Circular No. 470 (30 April 2025) sets 90% and repeals the old Circular No. 449.
Interest rate and monthly payment
The Calamity Loan costs 5.95% a year, which Pag-IBIG calls the lowest in the market. You repay it in equal monthly amortizations covering principal and interest. Here's roughly what that comes to:
| Loan amount | 12 months | 24 months | 36 months |
|---|---|---|---|
| ₱18,000 | ₱1,548.78 | ₱797.37 | ₱547.19 |
| ₱45,000 | ₱3,871.96 | ₱1,993.41 | ₱1,367.97 |
| ₱90,000 | ₱7,743.91 | ₱3,986.83 | ₱2,735.94 |
These are our estimates at 5.95% ÷ 12 a month, not Pag-IBIG quotes. Pag-IBIG also charges interest during the 3-month grace period and spreads it over the term, so your actual amortization will be a little higher. For comparison, the same ₱45,000 over 24 months on the Multi-Purpose Loan (1.4583% a month) is about ₱2,235.72.
Pag-IBIG Calamity Loan requirements
- Filled-out Calamity Loan Application Form (SLF066). Print it back to back on one sheet, in capital letters. Write the name of the typhoon or calamity, your loan term and your loan purpose.
- One valid ID. See Pag-IBIG's list of valid IDs.
- Proof of income (see the table).
- Cash card: a Pag-IBIG Loyalty Card Plus or a cash card from one of Pag-IBIG's partner banks.
- Applying online: a selfie showing your valid ID and your cash card.
| You are | Proof of income (any one, unless stated) |
|---|---|
| Employed in the Philippines | The Certificate of Net Pay at the back of the form, filled out by your employer, or a photocopy of your latest one-month payslip authenticated by the company's authorized signatory |
| Self-employed | ITR with audited financial statements and the tax payment receipt, plus DTI registration and a business permit; commission vouchers for the last 12 months; bank statements or passbook for the last 12 months (for remittances, pensions and similar income); a transport franchise (LGU for tricycles, LTFRB for other PUVs); a certificate of engagement from the business owner; or Pag-IBIG's Declaration of Income (HQP-SLF-136) |
| OFW | Within the past 12 months: an employment contract or POEA standard contract, certified by the POEA or a Philippine consular office; a Certificate of Employment and Compensation; or an ITR filed with the host country. Foreign-language documents need an English translation |
OFWs receiving the loan in a payroll account or disbursement card: submit a photocopy of the LandBank payroll account, or of the LandBank, DBP or UCPB cash card. If you apply through your employer, the employer certifies the photocopy. If you apply on your own, bring the card or account for authentication.
Pag-IBIG Checklist (PDF)MID number, contributions, housing loan rates, Multi-Purpose Loan and MP2. Free, no sign-up.DownloadHow to apply online (Virtual Pag-IBIG)
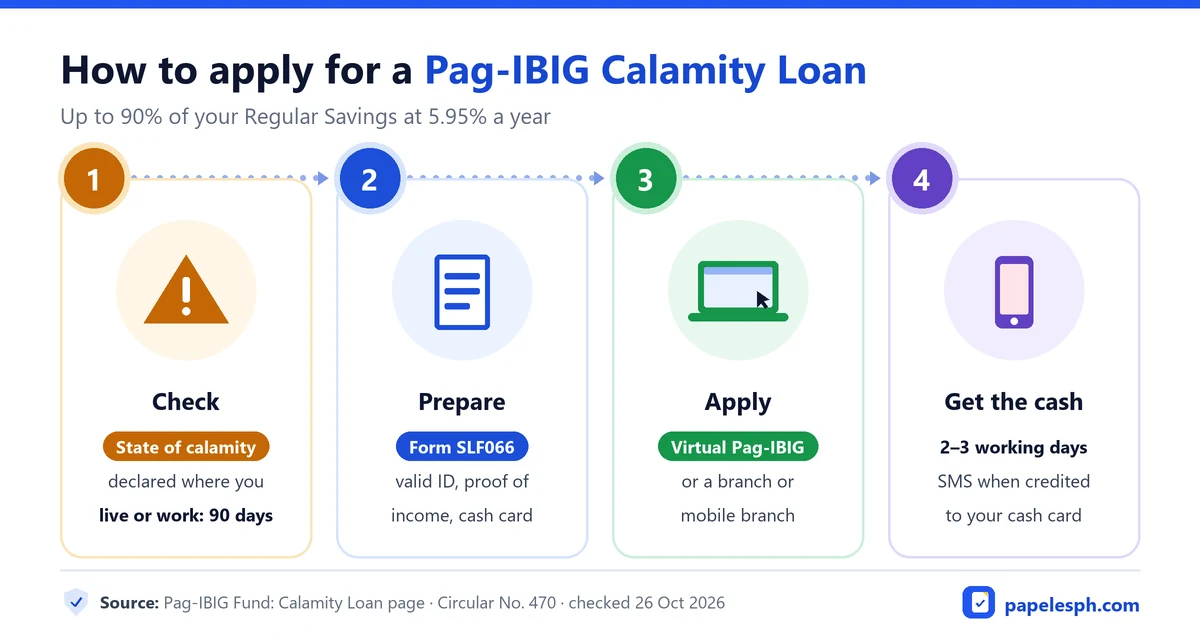
If your employer uses Virtual Pag-IBIG for Employers, you can fill out the Calamity Loan form online instead of uploading the paper form. This option is for Loyalty Card Plus holders only. Uploading the form works with a Loyalty Card Plus or a partner-bank cash card.
How to apply at a branch or a mobile branch
- Fill out the Calamity Loan Application Form and submit it with your requirements at the nearest Pag-IBIG branch, personally or through your employer. Processing starts only once your documents are complete.
- Get your STL Acknowledgment Receipt.
- Wait 2–3 working days for processing and validation.
- Get an SMS when the loan is credited to your cash card.
No branch nearby? Pag-IBIG's mobile branches, Lingkod Pag-IBIG on Wheels, also accept Calamity Loan applications and are sent to affected communities during calamities. Pag-IBIG says they served over 66,300 members in 2025.
Paying the loan
- Grace period: 3 months. Under Circular No. 470, payments are due on or before the 15th of each month, starting the 4th month from the release date. Pag-IBIG's web page puts it as "the 3rd month after the loan release", so check the first due date on your approved loan.
- Employees: by salary deduction. You can also pay ahead through Virtual Pag-IBIG or Pag-IBIG's accredited collecting partners.
- Self-employed and OFWs: through Virtual Pag-IBIG or the accredited collecting partners, in their outlets or online channels.
- Paying early: you can pay off the whole balance before the term ends.
- Late payment: 1/20 of 1% of the unpaid amount for every day of delay.
- Default: missing 3 consecutive amortizations, or 3 consecutive monthly savings, makes the whole balance due. Pag-IBIG then deducts it from your Regular Savings.
Another calamity in the same area? You can renew anytime. Your current Calamity Loan balance, with any interest and penalties, is deducted from the new loan.
Hardship: Pag-IBIG may offset your Calamity Loan balance against your savings on request for total disability, separation from work for health reasons, the death of an immediate family member, layoff or company closure, certain critical illnesses, or an OFW's repatriation.
Calamity Loan vs Multi-Purpose Loan
They're separate programs, so you can have both at the same time. Together with HELPs, your Pag-IBIG short-term loans can never go above 90% of your Regular Savings.
| Calamity Loan | Multi-Purpose Loan | |
|---|---|---|
| Who | Members in a declared calamity area, within 90 days | Any qualified member, any time |
| Interest | 5.95% a year | 1.4583% a month |
| Grace period | 3 months | 2 months |
| Renewal | Anytime if another calamity hits your area | After 4 payments, and at least 6 months after release |
| Form | SLF066 | SLF065 |
See the full Pag-IBIG Multi-Purpose Loan guide.
Not the SSS or GSIS calamity loan
SSS and GSIS run their own calamity loans, with their own rules and rates. This page covers only Pag-IBIG's. Being in a declared area may make you eligible for more than one, so check each agency.
Never pay a fixer. Apply only through Virtual Pag-IBIG, your employer, a Pag-IBIG branch or a Lingkod Pag-IBIG on Wheels unit. The loan goes to your own cash card, and nobody needs your Virtual Pag-IBIG password.
Official sources
- Pag-IBIG Fund Calamity Loan page: pagibigfund.gov.ph, checked 26 Oct 2026
- Pag-IBIG Fund Circular No. 470 (Enhanced Guidelines on the Calamity Loan Program, 30 April 2025)
- Calamity Loan Application Form, SLF066 (version 11, May 2025)
- Pag-IBIG Fund Circular No. 469 (MPL guidelines): the MPL, Calamity Loan and HELPs are separate programs
Frequently asked questions
How much can I borrow from the Pag-IBIG Calamity Loan?
Up to 90% of your total Pag-IBIG Regular Savings, which includes your contributions, your employer's contributions and dividends. With ₱50,000 in savings, that's up to ₱45,000. Any outstanding MPL, Calamity Loan or HELPs balance is deducted.
What is the interest rate of the Pag-IBIG Calamity Loan?
5.95% a year, according to Pag-IBIG Fund's Calamity Loan page and Circular No. 470.
Is the Pag-IBIG Calamity Loan still available?
It's available to members in areas under a declared state of calamity, for 90 days from the declaration. There's no single nationwide deadline, so check whether your city or municipality is under a current declaration.
Who is eligible for the Pag-IBIG Calamity Loan?
Members who live or work in a declared calamity area, apply within 90 days, have at least 12 monthly savings, are active (a contribution in the last 6 months, or 12 for OFWs), have no short-term loan in default, and can show proof of income.
Can I get a Calamity Loan if I have an existing Pag-IBIG MPL?
Yes. The Calamity Loan and the MPL are separate programs, so you can have both. Your outstanding balance is deducted, and all your short-term loans together can't exceed 90% of your Regular Savings.
How long does the Pag-IBIG Calamity Loan take?
Pag-IBIG processes applications in 2–3 working days and says you can get the loan in as fast as 3 days. You get an SMS when it's credited to your cash card.
Can I apply for the Pag-IBIG Calamity Loan online?
Yes, through Virtual Pag-IBIG under Apply for and Manage Loans → Apply for Short-Term Loan → Calamity Loan. You upload your valid ID and a selfie and enter your cash card or Loyalty Card Plus details.
What form do I use for the Pag-IBIG Calamity Loan?
The Calamity Loan Application Form, HQP-SLF-066, from any Pag-IBIG branch or Pag-IBIG's website. Print it back to back on one sheet and fill it out in capital letters.
When is the first payment of the Pag-IBIG Calamity Loan?
There's a 3-month grace period. Circular No. 470 says payments start on the 15th of the 4th month from the release date. Check the due date on your approved loan.
How much is the monthly payment?
At 5.95% a year, a ₱45,000 loan is roughly ₱1,993.41 a month over 24 months, or ₱1,367.97 over 36 months, before the grace-period interest Pag-IBIG adds.
Can I renew my Pag-IBIG Calamity Loan?
Yes, anytime another calamity is declared in your area. The balance of your current Calamity Loan, with any interest and penalties, is deducted from the new loan.
Is the Pag-IBIG Calamity Loan the same as the SSS calamity loan?
No. They're separate loans from separate agencies with their own rules. This guide covers only Pag-IBIG's.
Keep reading
Pag-IBIG Multi-Purpose Loan
How much you can borrow, the rate, requirements, online steps and loan status.
Read guidePag-IBIG contribution
₱200 + ₱200 a month, how to check and pay online, and when you can withdraw.
Read guidePag-IBIG MID number
Register online, verify your MID, retrieve a lost number and update records.
Read guidePag-IBIG MP2 savings
Requirements, how to open and check your account, and how to claim or withdraw it.
Read guideSources
- Pag-IBIG Fund: Calamity Loan (checked 26 Oct 2026)
- Pag-IBIG Fund Circular No. 470, Enhanced Guidelines on the Calamity Loan Program (30 April 2025, PDF)
- Calamity Loan Application Form (SLF066, V11 05/2025, PDF)
- Pag-IBIG Fund Circular No. 469, MPL guidelines (separate short-term loans, PDF)
- Virtual Pag-IBIG: apply for a short-term loan
- Virtual Pag-IBIG: Loan Status Verification
- Pag-IBIG branch
Last checked 26 October 2026. See how we research and the updates log.